
Morgan Stanley (MS) is currently enjoying the kind of week that investment bankers dream about when they are still in business school. The firm, alongside its perennial rival Goldman Sachs, has secured a lead role in the Anthropic IPO. This is not just about the fees, though the fees will be substantial. It is about the institutional halo effect. In a market where artificial intelligence is the only narrative that seems to matter, being the chosen gatekeeper for a major AI listing is the ultimate strategic flex.
The financial reality of the firm remains grounded in a surprisingly reasonable valuation. While the broader market chases tech multiples that defy gravity, Morgan Stanley (MS) trades at a trailing price to earnings ratio of 14.7. For a company that grew revenue by 10.8 percent year over year and maintains a net cash position of 131.58 billion dollars, this is what fundamental analysts call a durable capital structure. According to the latest Form 10-Q filed in August, the firm continues to navigate a high interest rate environment with a massive total cash pile of 739 billion dollars, providing a significant buffer against the 5.10 percent yield on the US 10-Year Treasury.
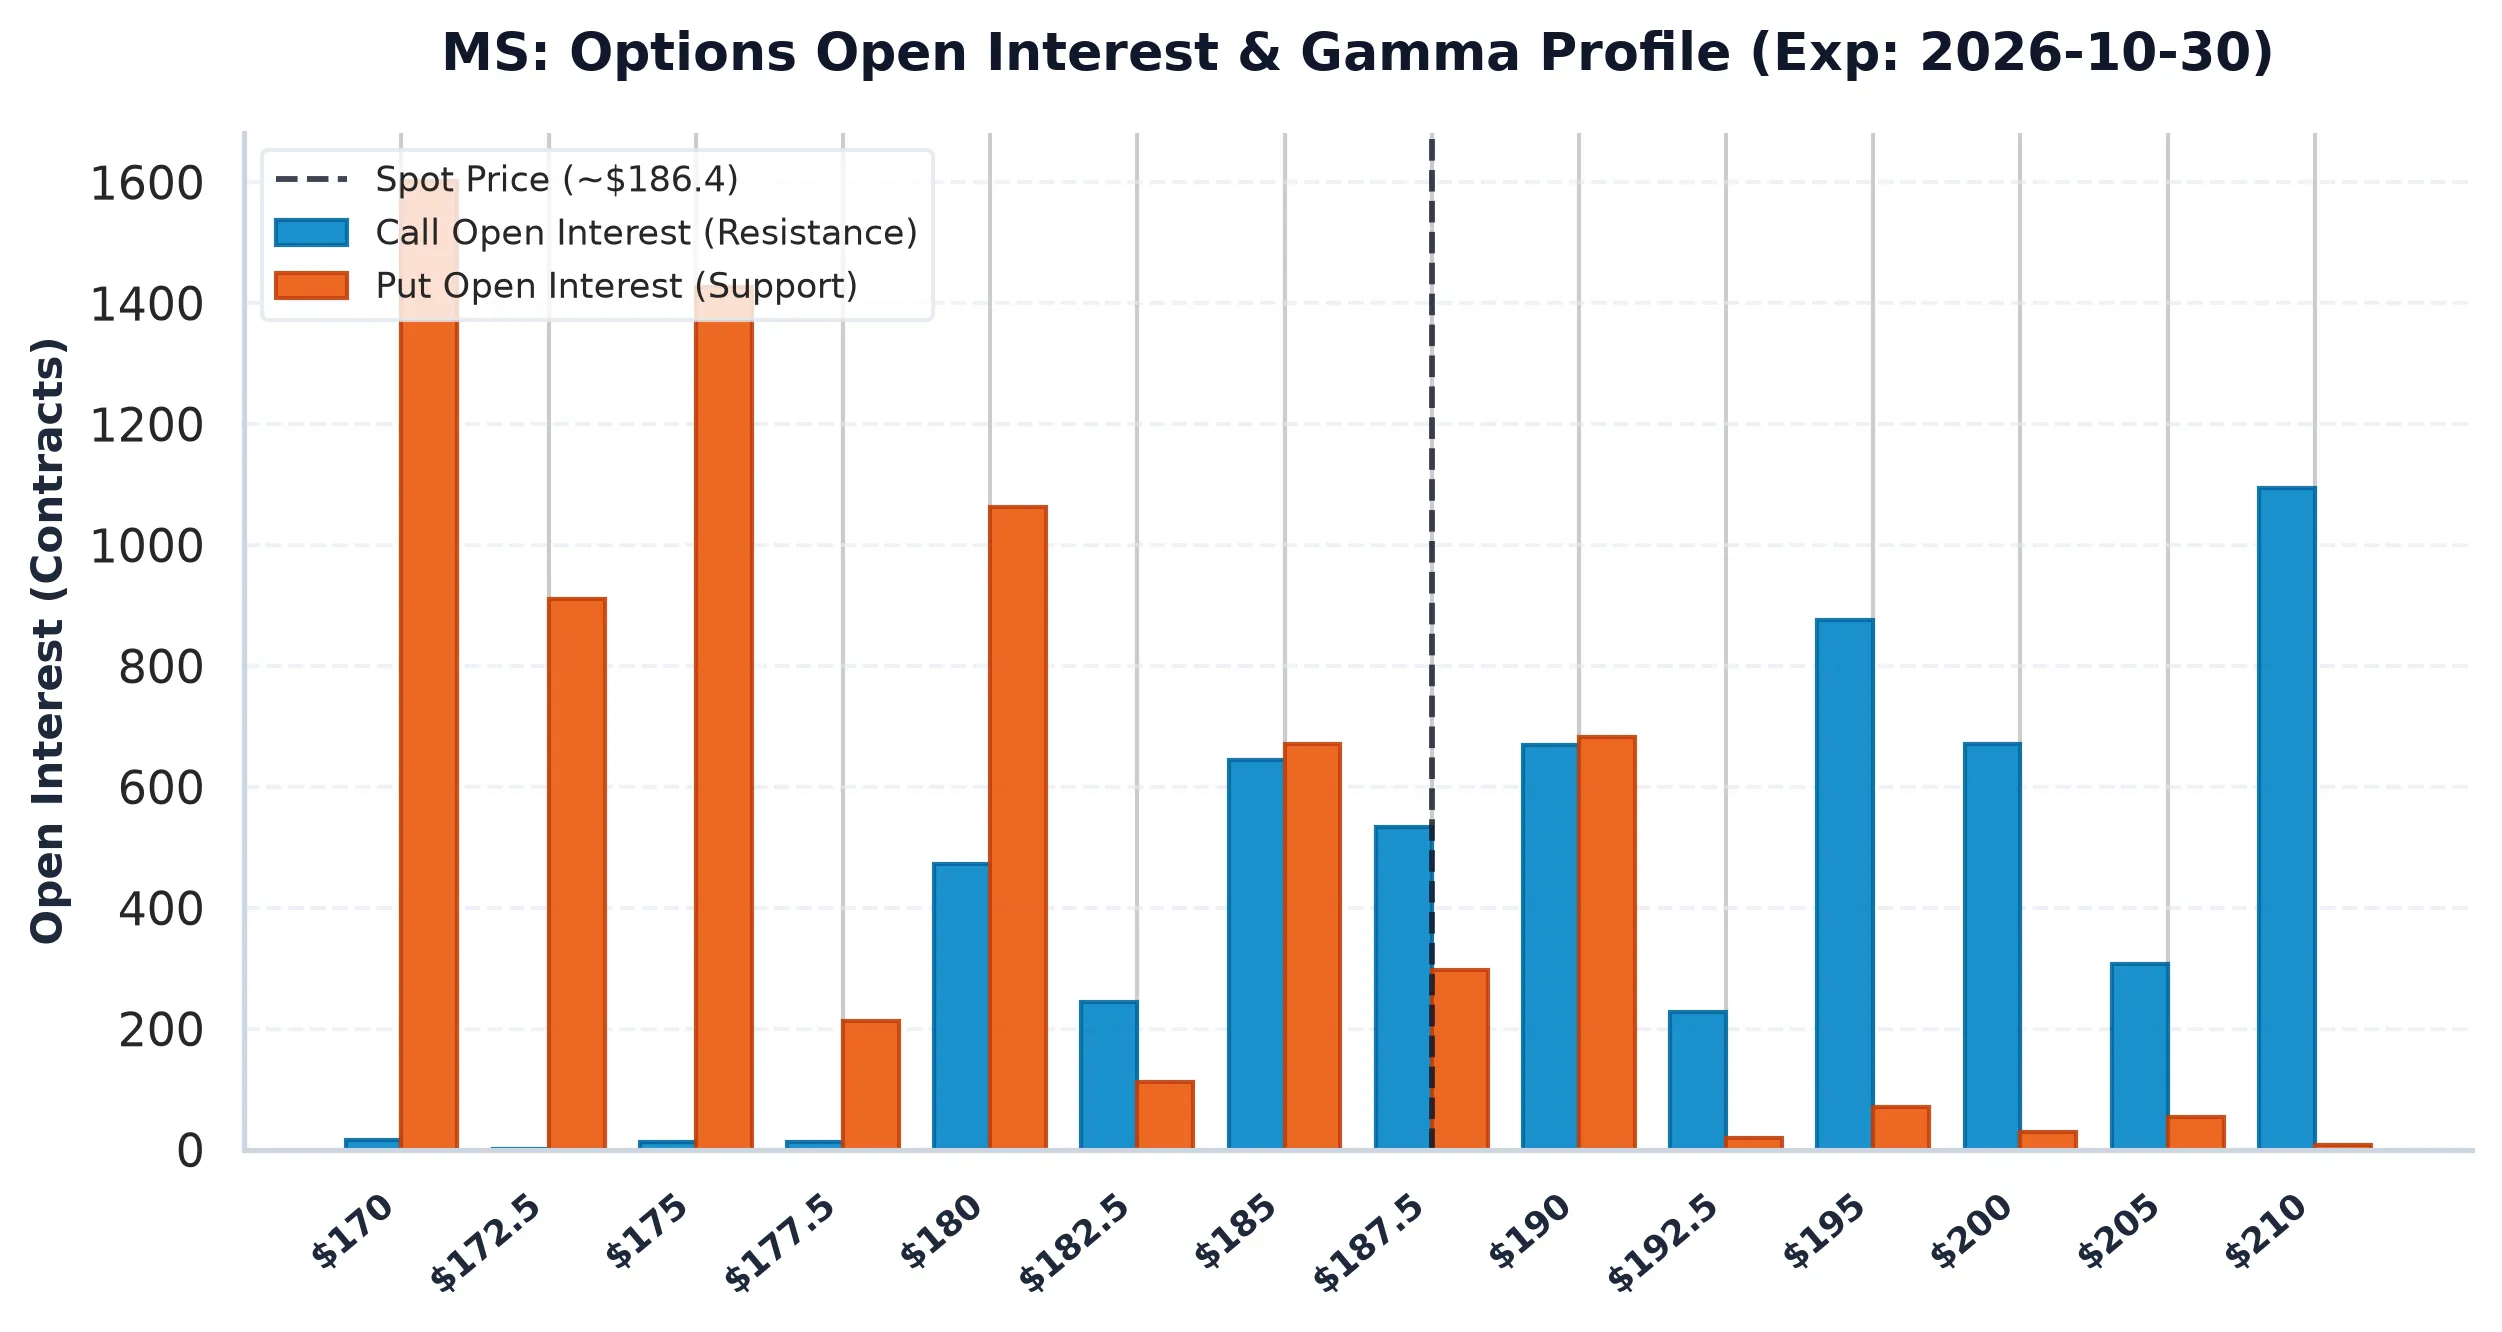
While the fundamental story is one of prestige and cash, the market structure story is one of surgical precision. The stock is currently trading at 186.38 dollars, which is remarkably close to the Max Pain strike of 185.00 dollars. In the world of equity derivatives, this suggests a magnetic pinning effect. Options dealers are currently holding a neutral gamma bias, meaning they are not forced to chase the stock higher or sell it lower to hedge their books. The Put/Call Open Interest ratio is 1.03, a figure so balanced it almost looks intentional.
There is a formidable Call Wall at 190.00 dollars, represented by over 3,000 contracts. This acts as a structural ceiling. Unless the Anthropic IPO enthusiasm turns into a full blown mania, Morgan Stanley (MS) is likely to find heavy resistance as it approaches that round number. On the downside, a Put Wall at 170.00 dollars provides a floor. The market is essentially pricing in a quiet period of consolidation, with an expected 30 day move of roughly 10.89 percent in either direction.
The firm is also making headlines for its wealth management advice, specifically suggesting that family financial decisions should not be made in silos. This is a charming sentiment, but the institutional reality is that Morgan Stanley (MS) is a massive, integrated machine designed to capture capital flows wherever they appear. Whether it is advising families on their estates or taking the next great AI hope public, the firm is positioning itself as the indispensable intermediary of the current capital cycle.
For investors, the question is whether the IPO prestige can translate into a higher multiple. At 13.6 times forward earnings, the market is still pricing the firm as a traditional financial services entity rather than a high growth tech enabler. If the Anthropic deal goes off without a hitch, that perception might finally begin to shift, though the 190 dollar Call Wall remains the immediate hurdle for the bulls to clear.
Morgan Stanley (MS)
Trailing P/E
Marcus Wolfe Screen
Leverage Profile
30D Channel
Banking liquidity & regulatory capital compliant (Basel III / CET1 governed); deposit & trading settlement flows normalized.
Tier 1 Regulatory Capital & Liquidity Coverage Ratio (LCR) compliant; balance sheet governed by Basel III capital buffers.
Evaluated against 5.10% US 10-Yr Benchmark; bank net interest margins sensitive to yield curve slope (2s10s spread) and deposit beta.
Max Pain: $185.00 (-0.74%) | P/C Ratio: 1.03 | 30D Channel: $173.02 – $199.74.
$171.47 – $178.92 (-4% to -8% Pullback Accumulation)
Sustained weekly close below $167.74 (-10.0% structural stop) or fundamental cash flow deterioration.